What project owners need to know.
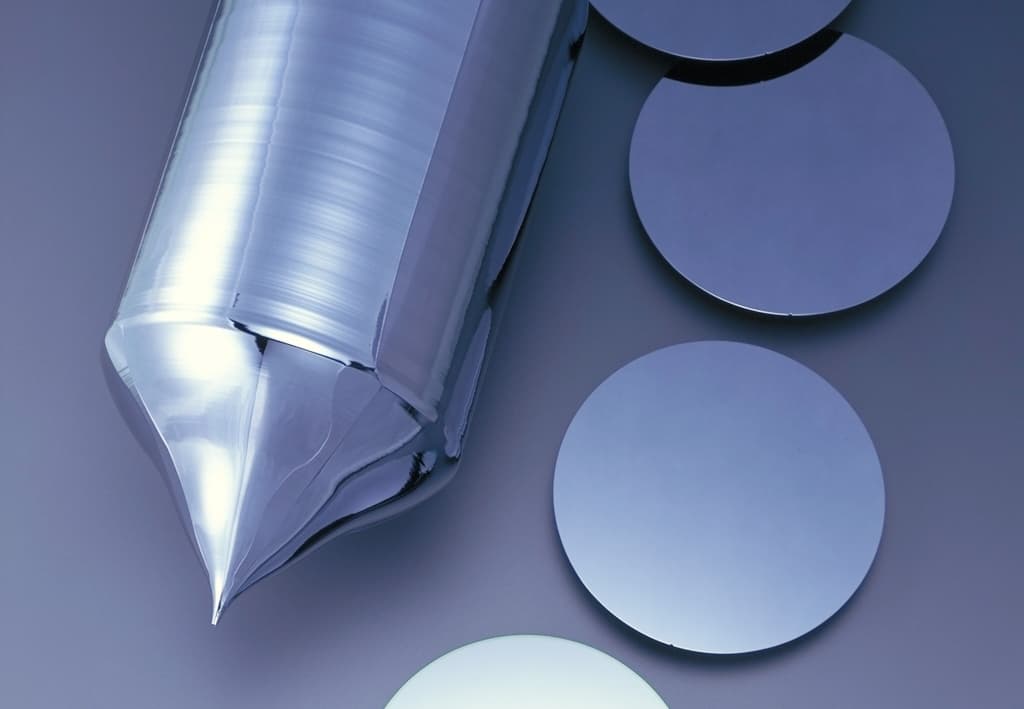
India's proposed polysilicon scheme is a planned central incentive for domestic solar-grade polysilicon, the feedstock that is melted to grow every silicon ingot. Angel One reported on 21 October 2026 that the Finance Ministry had cleared the proposal in principle and that the renewable energy ministry hoped to take it to the Cabinet within a month. The scheme has not been notified and its support mechanism has not been disclosed. The stated ambition is about 30 GW of polysilicon capacity by 2030, while Mercom reported in September 2026 that domestic production had yet to begin.
What was reported, and what is still unconfirmed
Angel One reported on 21 October 2026 that the Finance Ministry had cleared, in principle, a proposal to support polysilicon manufacturing in India, and that the renewable energy ministry hoped to place it before the Cabinet within a month. The same report repeated the goal of 30 GW of polysilicon capacity by 2030, which it estimated would need about ₹25,000 crore of investment, and said the government was also considering separate support for ingots and wafers and for solar glass. The report did not disclose how the support would work.
The October step follows months of discussion. PV Tech reported on 7 August 2026 that a production-linked incentive could cover more than 10 GW of polysilicon capacity, and ETV Bharat quoted the MNRE Secretary on 21 August 2026 on the 30 GW by 2030 goal. Other outlets have attributed the first report of the in-principle approval to Business Standard; we could not read that article's full text, so this guide cites the report we were able to verify. Until a scheme is approved by the Cabinet and notified, its form (production-linked incentive or upfront capital support), size, eligibility and timelines should all be treated as unknown.
- Reported: in-principle Finance Ministry clearance (21 October 2026)
- Pending: Cabinet approval, notification and scheme guidelines
- Not disclosed: support mechanism, incentive size and capacity floor
- Stated goal: about 30 GW of polysilicon capacity by 2030
Why polysilicon is the missing link in India's chain
India now has a large module base, a growing cell base under ALMM List-II and a small but growing ingot-wafer base. Polysilicon is the stage with no commercial domestic output. Mercom reported on 11 September 2026 that the announced domestic polysilicon pipeline had reached about 30 GW, but that production had yet to begin. Until it does, every Indian ingot plant melts imported polysilicon.
The ingot-wafer stage is also thin. The Centre for Science and Environment estimated India's operational ingot-wafer capacity at about 2 GW as of April 2026, against the 80 GW ingot-wafer target for June 2028 reported by PV Tech. A polysilicon scheme addresses the feedstock end of that gap; it does not by itself add crystal growers or wafering lines.
- Polysilicon: announced pipeline about 30 GW, production yet to begin (Mercom, Sept 2026)
- Ingot-wafer: about 2 GW operational, April 2026 (CSE)
- Policy target: 80 GW ingot-wafer capacity by June 2028 (PV Tech)
What it means for ingot and wafer makers
For ingot makers the scheme is mainly about feedstock security and origin. Domestic polysilicon would reduce exposure to a single import source and to trade measures that look at where polysilicon was made, such as the US polysilicon rules covered in our separate guide. MNRE's proposed ALMM List-II cell code, reported by PV Tech on 7 October 2026, would also mark whether the polysilicon, ingot, wafer and cell inside a cell are domestic or foreign, which makes upstream origin visible in the product code itself.
Timing matters. Polysilicon plants are large chemical facilities that typically take years to build and qualify, so domestic feedstock is unlikely to reach ingot lines before ALMM List-III begins on 1 June 2028. Ingot and wafer projects planned now should assume imported polysilicon for their first years of operation, with qualified alternative sources, and treat domestic polysilicon as an upside rather than a dependency.
- Plan for imported polysilicon in early operating years
- Keep origin documentation for polysilicon lots from day one
- Watch the List-II cell-code proposal, which would expose upstream origin
- Wafer enlistment under List-III is tied to equivalent ingot capacity
What it means for quartz crucibles and HPQ sand
Every Czochralski pull melts polysilicon in a fused-quartz crucible, so ingot output drives crucible and high-purity quartz (HPQ) sand demand whatever the origin of the polysilicon. The reported scheme concerns polysilicon; nothing reported so far extends it to crucibles or quartz. Indian ingot makers will therefore still need a qualified crucible supply and, behind it, crucible-grade HPQ sand, a material with highly concentrated global supply.
That is why we read the scheme as one piece of a longer chain: quartz to HPQ sand to crucible on one side, metallurgical silicon to polysilicon on the other, both meeting at the ingot puller.
What to watch next
The next signals are Cabinet approval, the notified guidelines and the support mechanism. Beyond the scheme itself, the ALMM List-III first-list trigger matters: the initial list for ingots and wafers is to be issued once at least three independent manufacturers with a combined 15 GW are available, according to PIB. We will update this guide when primary documents are published.
- Cabinet decision and notification text
- Form of support: production-linked or capital support
- Minimum capacity and integration conditions
- Any parallel support for ingots, wafers or solar glass
- Progress toward the List-III trigger of three units and 15 GW
How JRST supports this requirement
JRST works across the upstream silicon chain, from high-purity quartz sand and crucibles to crystal growth and wafering. Silicon Ingot Technology, a JRST Technology-led unit in Nagpur reported as Maharashtra's first silicon-ingot plant, completed its first pilot batch in April 2026. This guide summarises public reporting as of 25 October 2026; scheme details are not final, and their effect on any project must be confirmed against the notified scheme and with appropriate advisers.
Discuss your requirement
Mohammed Saif Zaveri connects JRST's industrial content to execution conversations.
As Co-Founder and designated partner of JRST Technology LLP, Mohammed Saif Zaveri works across industrial growth, strategic partnerships, client conversations, equipment strategy, and project pathways for silicon, solar, semiconductor, and advanced-manufacturing opportunities.
This knowledge page is part of JRST's public industrial knowledge base, designed to help buyers move from search terms and early research toward a structured technical-commercial discussion.
View Mohammed Saif Zaveri's profileConnect on LinkedInFrequently asked questions
Has India approved a polysilicon manufacturing scheme?
Not fully. Angel One reported on 21 October 2026 that the Finance Ministry had cleared the proposal in principle. Cabinet approval and notification were still pending, so the scheme's terms may change.
How much polysilicon capacity does India want?
The stated goal is about 30 GW of polysilicon capacity by 2030, as reported by ETV Bharat from the MNRE Secretary in August 2026. Earlier reports said a first incentive could cover more than 10 GW.
Does India produce polysilicon today?
Not at commercial scale. Mercom reported on 11 September 2026 that about 30 GW of polysilicon capacity had been announced but that production had yet to begin.
Why does polysilicon matter for silicon ingots?
Polysilicon is the feedstock that is melted in a quartz crucible and pulled into a monocrystalline ingot by the Czochralski method. Without domestic polysilicon, Indian ingots are grown from imported feedstock.
Will the polysilicon scheme cover ingots and wafers?
The October report said the government was considering separate support for ingots and wafers, but no such scheme had been announced. Ingots and wafers are separately covered by ALMM List-III from 1 June 2028.
Primary sources and further reading
Last reviewed 2026-10-25. Technical scope, policy eligibility, availability, and commercial terms should be independently confirmed for each project.